

“Who is right: the big money from central banks downwards, or the little people who have a record of buying at the top and selling at the bottom?”
In recent weeks, open interest on Comex gold and silver contracts has struggled higher but is still close to deeply oversold territory. This reflects speculators putting just a toe in the water. Using their language, they are yet to be fully convinced that the debasement trade is on, so they believe gold and silver are vulnerable to rising bond yields. Hence, the opportunity for market makers and bullion bank trading desks to cover shorts and attempt to build neutral to long positions. But open interest tells us that this shakeout has its limitations:
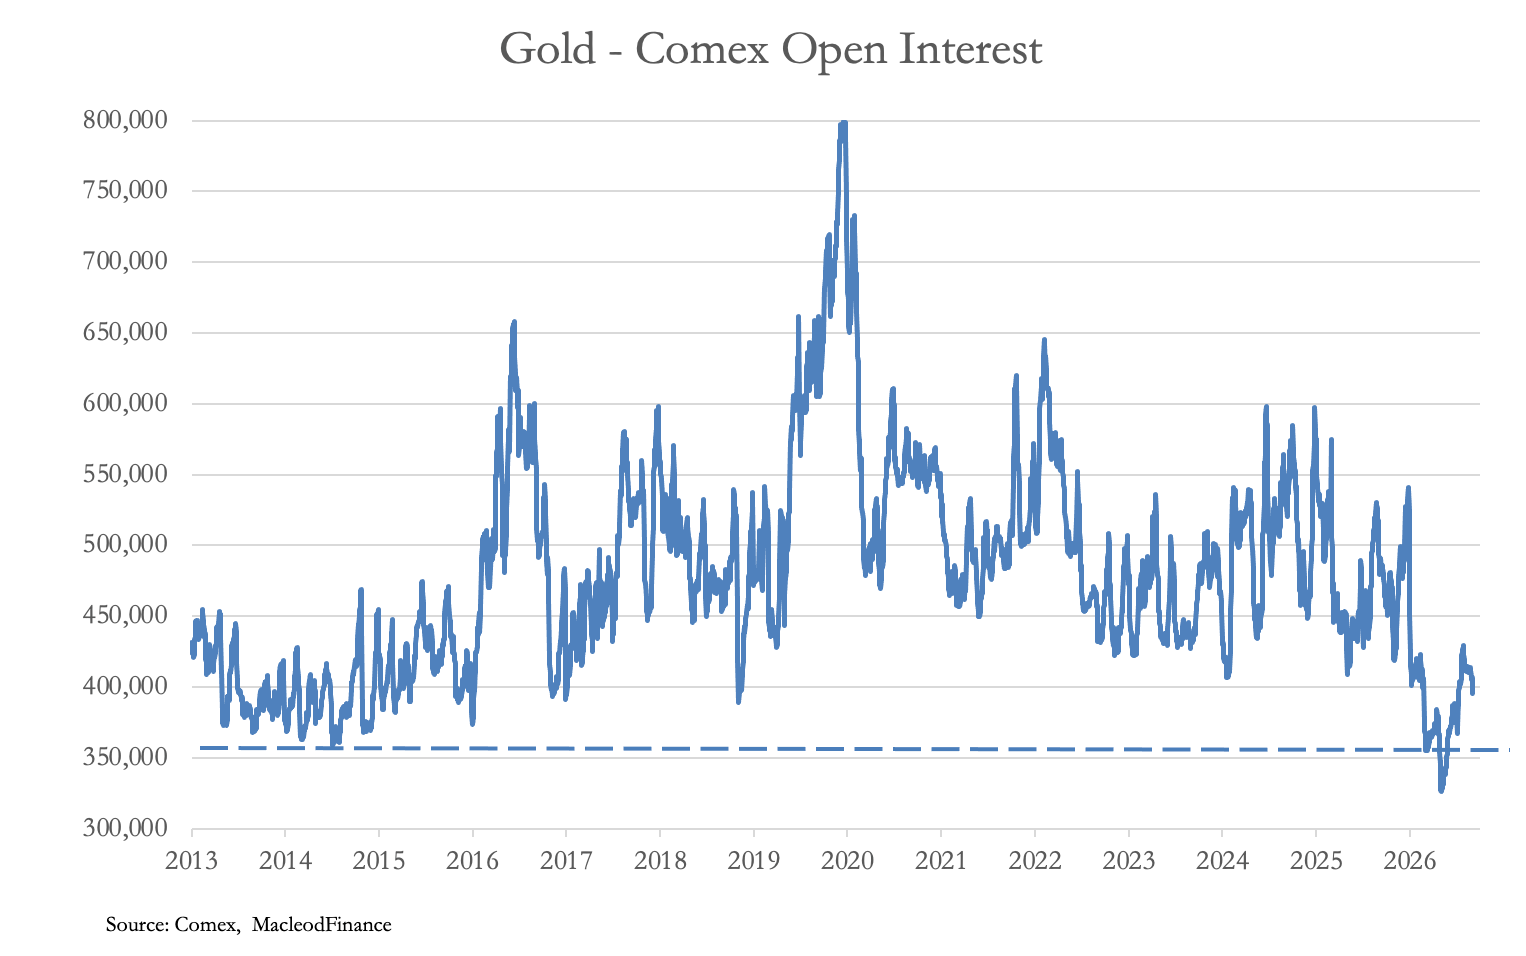
As a measure of an oversold market, open interest is still struggling to rise above the extreme levels at the end of the 2011—2015 bear market. The fact that market makers have been trying hard to close their bears and go long tells us that they expect prices to rise from here and need to be positioned accordingly.
To confirm the bullish thesis, deliveries on the October contract expiry rose sharply: 11,465 gold contracts representing 35.66 tonnes, and 2,125 silver contracts representing 330.47 tonnes. So far, in 2026 600.6 tonnes of gold and 9,000.65 tonnes of silver have stood for delivery. Furthermore, China’s customs data records 1,141 tonnes of gold imported by end-August and there’s a further 80 tonnes of monetary gold added to the PBOC’s official reserves.
To summarise, while Western retail demand is virtually non-existent, China and other Asian nations are using the opportunity to get out of the dollar and into gold in huge quantities. Who is right: the big money from central banks downwards, or the little people who have a record of buying at the top and selling at the bottom?
We will leave that question hanging and move our attention to bonds. All bond markets are in crisis with yields rising to levels exposing the bankruptcy of the dollar-
